Nairobi, November 2, 2026... You have heard about insurance, learned about its benefits, and finally bought a policy. But months or years later, your life begins to change.
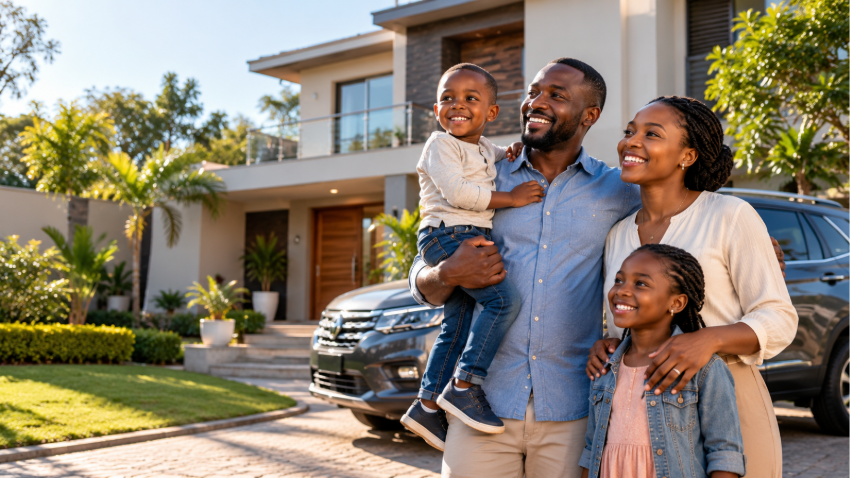
Family stands outside their home with their car, representing the assets and family responsibilities that insurance can help protect.
Read More: 10 Things You Didn’t Know You Could Insure
You buy your first car or upgrade to a second one. The love bug bites, and you get married, welcome children, move into a bigger house or acquire more household appliances.
If you are an entrepreneur, your business has grown, you may have more employees, and you may now own more stock and equipment.
But what do these changes have to do with the insurance policy you bought for yourself, your dependants, your business or your employees?
It’s quite a lot. The cover that suited you when you first bought it may no longer reflect what you own, the people who depend on you or the risks you face today. You could be paying for protection you no longer need while overlooking risks that deserve attention.
Here are five things to check to ensure your insurance keeps pace with your life.
1. Has your family grown?
Marriage, having children or taking on a mortgage can change your financial responsibilities. Life insurance and medical cover that once suited your needs may require a second look.
Review your policies to establish whether they still meet your family's needs. Where applicable, ensure your beneficiaries' details are up to date. This could mean contacting HR to add a new dependant to your employer-provided medical cover or checking whether newly recruited employees have been enrolled in the relevant staff benefits, such as medical and group life insurance.
If you are a business owner, review your employee protection arrangements as your team grows. Explore the insurance solutions available through Equity to understand the options that may suit your needs.
2. Are you paying for similar benefits twice?
You may have personal insurance alongside benefits provided by your employer. Some policies may cover similar things, such as medical expenses or life benefits, meaning you could be paying for protection that partly overlaps.
However, similar benefits do not always provide identical protection. One policy may have a higher limit, cover different expenses or apply under different conditions.
Reviewing your policies can help you identify unnecessary duplication and spot gaps in your protection. Before cancelling any policy, compare the benefits carefully and seek advice from your insurance provider.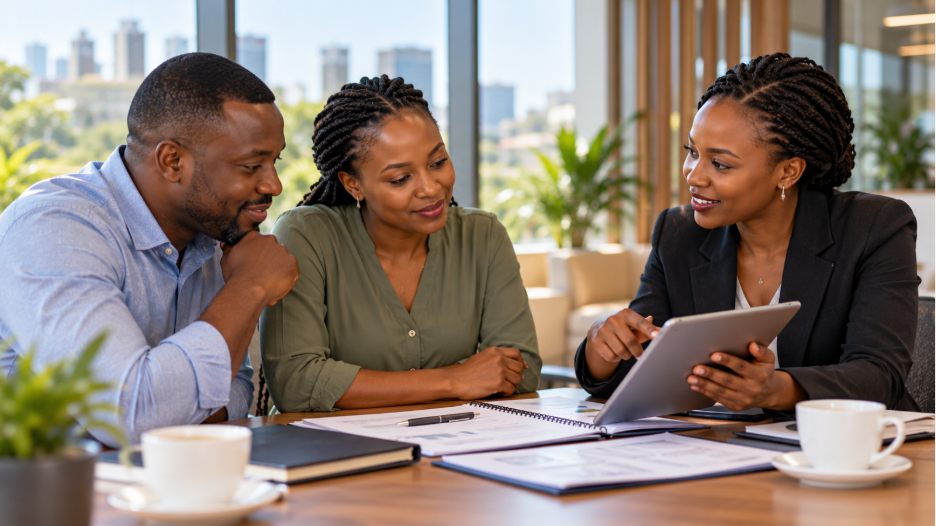
A couple consults an insurance adviser to review their policy and understand their available coverage options.
3. Have your assets grown?
When you first insured your home or business, you may have owned fewer assets. Today, you could have more furniture, electronics, equipment, or business stock.
For example, imagine you insured stock worth KSh500,000 when opening a shop. Two years later, the stock is worth KSh2 million, but the insured value remains unchanged. If a fire or another insured event destroys the stock, your cover may not be enough to meet the loss, leaving your business facing a significant setback.
Be sure to review your insured values whenever you acquire valuable assets, renovate your home or expand your business.
An entrepreneur reviews business records and documents in a well-stocked shop as the business grows.
4. Do you understand what your policy covers?
Having insurance does not automatically mean every loss is covered. Policies have exclusions, limits, excesses and conditions that determine how protection works.
Take time to understand these terms, including the documents and deadlines required when making a claim. Keep your policy documents and payment records safe, and ask your insurer to explain anything unclear.
5. Can you keep your cover active?
After reviewing your family's needs, checking your assets and understanding your policy, remember one more important thing: your cover must remain active for you to benefit from it, subject to the policy's terms and conditions.
Keep track of premium due dates and renewal dates, and set reminders so you do not accidentally let your cover lapse. If paying your annual motor insurance premium in one instalment is challenging, there are options worth exploring before your renewal date.
Equity's Insurance Premium Financing solution allows eligible customers to explore financing their motor insurance premiums, subject to applicable terms and conditions. Before committing, understand the costs, repayment schedule and eligibility requirements.
Is your insurance keeping up with your life?
Your insurance needs should evolve as your life changes. Whether you have welcomed a new family member, bought a car, expanded your business or acquired valuable assets, take time to review your policies and ensure your cover reflects your current circumstances.
Don't wait until you need to make a claim to discover that your protection is no longer adequate.
Visit your nearest Equity branch or contact Equity Insurance via +254 763 000 000 or info@equitybank.co.ke , or visit the Equity Insurance website to explore available insurance solutions and find out how you can protect what matters most. You can also request a callback to discuss your insurance needs.
Protecting your future starts with having the right cover today.